Well report No. RR-9605 · T3N · R16W · SEC 27 · filed October 10, 2026
Oilfield ServicesWell report
Oilfield Service Capacity Re-Tightens Across U.S. Shale Plays
An oilprice.com piece headlined "The Oilfield Service Crunch Is Here" flags renewed tightening in U.S. oilfield service capacity, putting completion scheduling, frac crews and OCTG supply back on the operator watch list.
Field notes
- oilprice.com published the alert under the headline 'The Oilfield Service Crunch Is Here.'
- Service tightness flagged across U.S. shale basins including the Permian, Bakken, and Eagle Ford.
- Strain vectors named: pressure pumping and fracturing fleets, OCTG and line pipe supply, and sand/water logistics.
- No specific bpd, rig-count, or pricing figures disclosed in the source headline.
- Watch metrics: service-firm utilization, frac-spread count, OCTG mill lead times, completion-timing slippage.
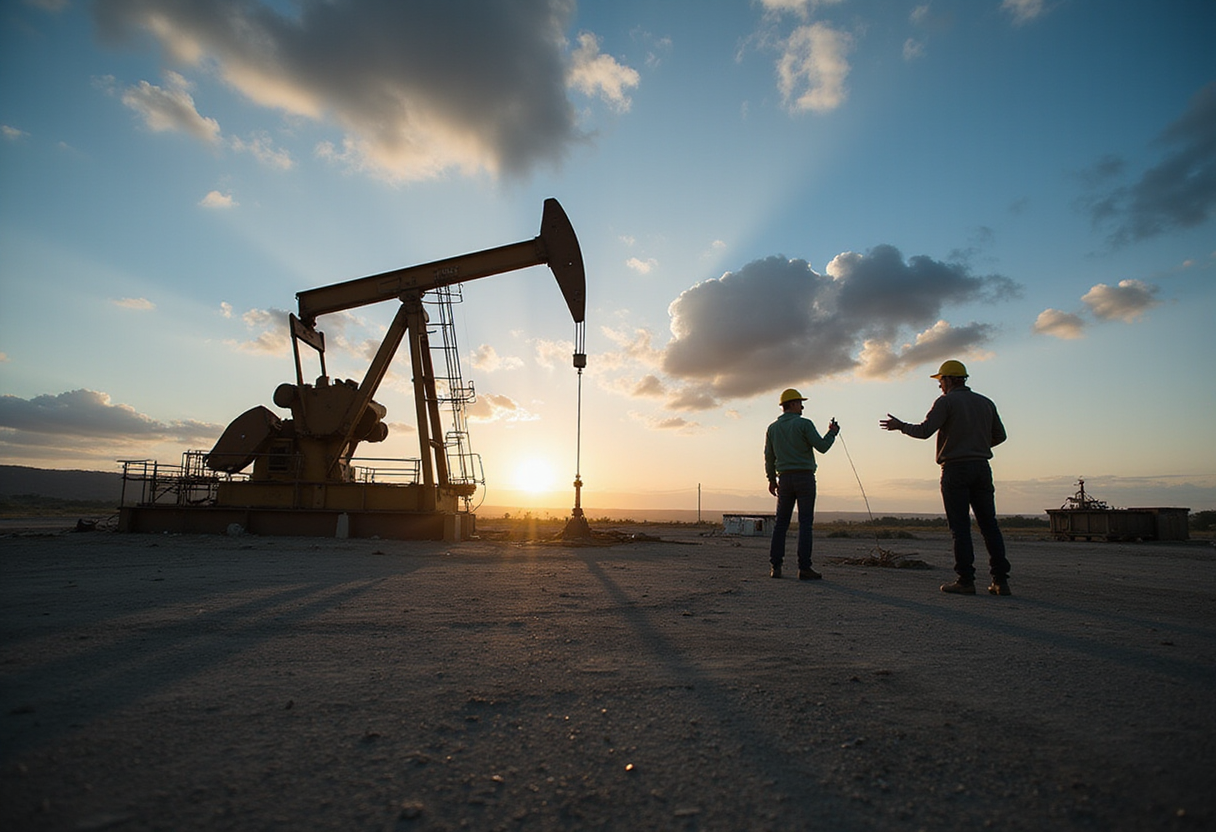
Oilfield service capacity across U.S. shale basins is once again tightening, according to an oilprice.com piece headlined "The Oilfield Service Crunch Is Here."
The alert tracks a recurring dynamic in the U.S. completions market. Whenever active rig counts hold above the level the service sector sized for during a downturn, completion windows book out, pressure pumping utilization rises, and tubular supply tightens on the same calendar quarter.
Where the strain shows first
Service tightness typically surfaces in three vectors at once:
- Pressure pumping and fracturing crews — horsepower utilization compresses the completion calendar before anything else.
- OCTG and line pipe — domestic mill output and import flow lag the order book.
- Sand, water, and last-mile logistics — terminal-of-record capacity and produced-water handling pinch during stacked pad programs.
In the Permian, where disposal-well capacity and produced-water pricing already reflect basin-level infrastructure, the constraint shows up in completion schedules first. In the Bakken and Eagle Ford the same dynamic surfaces through crew allocation rather than water handling.
What it does to operator planning
A tight service market compresses scheduling flexibility before it touches commodity prices.
The operational adjustments track a familiar pattern:
- Completion schedules lock in further ahead in the planning cycle.
- Stage counts and lateral lengths get fixed months ahead of spud.
- Sand and stimulation-chemical procurement shifts from spot to term contracts.
- Crew allocations book across multi-well pads rather than single wells.
For tier-one development programs in the Permian, Bakken, and Eagle Ford, completion timing often sets the rig-program pace. A one-quarter slip in frac-crew availability pushes production timing out by the same interval, even with rigs running flat out.
Why this is a planning problem, not a price problem
Service tightness does not move WTI or Brent. It moves the operator's calendar and capital cost per barrel. Service-cost inflation appears in capital-guidance line items and completed-well cost reports, not in commodity prices.
For integrated portfolios, the supply-chain implications extend through tubular goods, stimulation chemicals, and water logistics. For pure-play E&Ps, the constraint shows up more visibly through completion-timing slippage flagged in earnings calls and operating updates.
What the headline does not tell us
The oilprice.com headline does not, on its own, disclose the specific metrics behind the framing. The standard watch list applies:
- Service-firm utilization commentary in the next round of quarterly results from SLB, Halliburton, and Baker Hughes.
- Frac fleet additions and retirements against active crew count.
- OCTG pricing and mill lead times from domestic producers.
- Operator disclosure of completion-window timing changes in earnings transcripts.
- Permian disposal-well capacity and produced-water pricing moves.
Watch items
- Active frac-spread count versus rig count in the Permian and Eagle Ford.
- Service-cost inflation guidance inside operator capex updates for the remainder of 2025.
- OCTG import flows against domestic mill lead times.
- Completion-stage count versus plan in operator earnings calls.
- WTI-Brent spread and basin differentials as activity proxies.
via Google News: Oilfield services (Source)
More from Priya Raman
Show full bio
Senior reporter covering media and advertising at Rig & Refinery.
381 articles