Well report No. RR-5102 · T4N · R11W · SEC 28 · filed November 6, 2026
OffshoreWell report
Yinson Azalea raises $1.45bn to refinance Agogo FPSO debt
Yinson Azalea’s US$1.45 billion secured bond refinanced Agogo FPSO debt offshore Angola. Advisers call it the largest FPSO project bond yet and the first outside Brazil.
Field notes
- $1.45 billion senior secured bond offering refinanced existing Agogo FPSO debt.
- Agogo is chartered to Azule Energy Angola under a 15-year agreement.
- The offering used Rule 144A and Regulation S of the US Securities Act.
- Advisers call it the largest FPSO project bond to date and the first outside Brazil.
- Singapore security includes a vessel mortgage, issuer share charge and accounts charge.
By Priya Raman
US$1.45 billion is the headline figure in Yinson Azalea Production’s senior secured bond offering for the Agogo floating production, storage and offloading (FPSO) vessel offshore Angola. The proceeds refinanced existing project debt on the vessel, according to transaction counsel.
The offering was issued under Rule 144A and Regulation S of the US Securities Act. Transaction advisers describe it as the largest FPSO project bond issued to date. It is also the first FPSO project bond for a project outside Brazil. Those are milestone claims, not disclosed measures of yield or investor returns.
The disclosed transaction is a refinancing. It does not announce a new field sanction, appraisal-stage project or additional FPSO order. The cash-flow claim rests on an operating vessel and its charter, rather than an undeclared development program.
Yinson Azalea is registered in Singapore. It is a subsidiary of Yinson Production, a global independent FPSO owner and operator. Yinson Production sits within Malaysian energy infrastructure group Yinson Holdings.
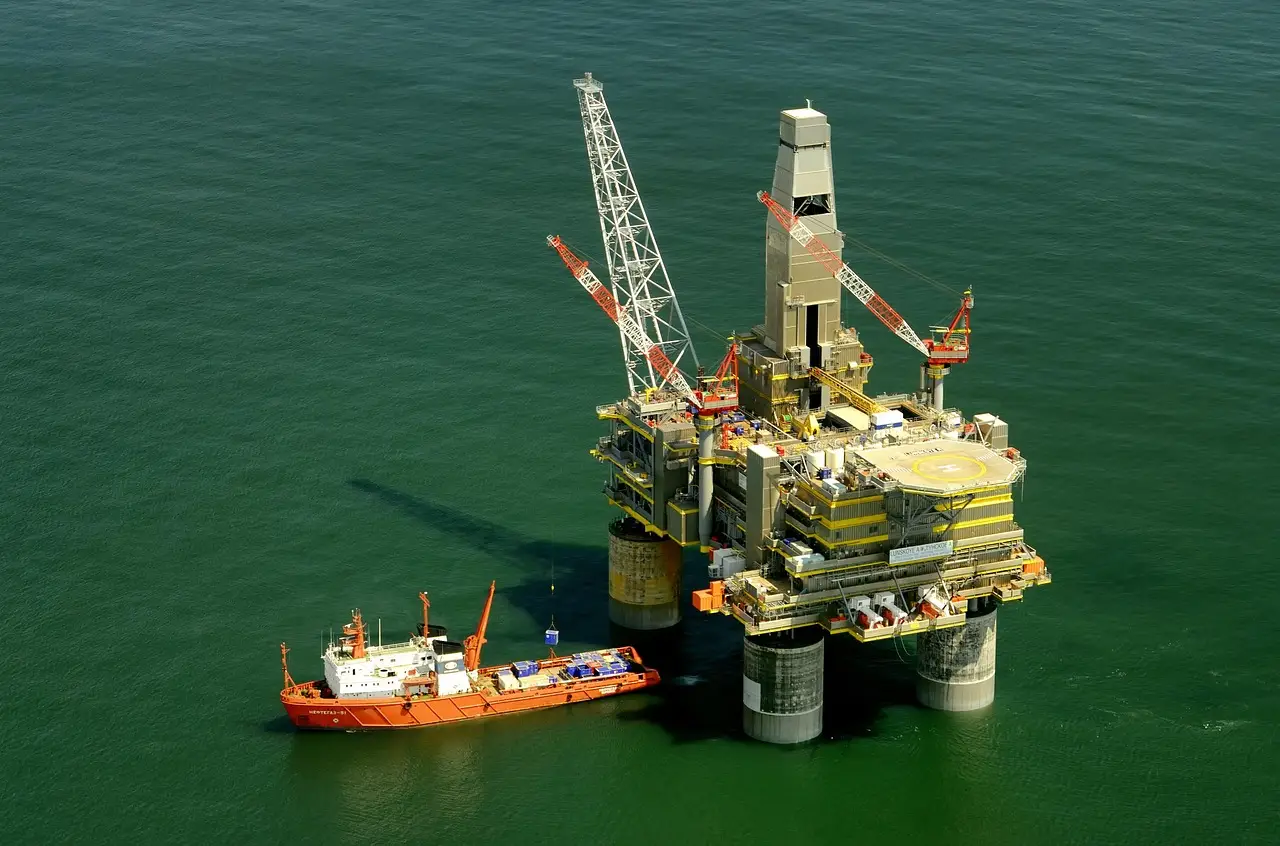
Agogo processes and stores oil extracted at sea before transferring it for transport. Azule Energy Angola charters the vessel under a 15-year agreement. The announcement discloses no FPSO capacity, production rate, reserve base or charter value. Those omissions limit any assessment of the refinancing.
Takeaway: This is debt refinancing around an operating Angola FPSO, not a new oil-supply promise.
What security backed the US$1.45 billion deal?
The disclosed Singapore-law collateral package contains three core interests:
- a vessel mortgage over Agogo;
- a share charge (security over the issuer’s shares); and
- an accounts charge (security over accounts).
Singapore counsel coordinated the release of outgoing security and the creation and perfection (completion through filings and registrations) of the incoming security. The work covered several jurisdictions, with filings and registrations involving Singapore’s Accounting and Corporate Regulatory Authority and Maritime and Port Authority.
Associate director Heather Chong told Asia Business Law Journal: “As Singapore counsel to the issuer, we advised on the Singapore law aspects of the bond issuance.”
Singapore law mattered because Agogo is Singapore-flagged. The issuer, its shareholder and the FPSO operator’s shareholder are also Singapore-incorporated entities. TSMP Law Corporation prepared and reviewed the Singapore-law disclosures in the offering memorandum.
Partner June Ho said: “The attractive pricing also demonstrates strong institutional investor appetite for FPSO project bonds and the growing role of capital markets as a viable source of long-term financing for offshore energy infrastructure.”
That statement is attributed market commentary. The source gives no coupon, yield, tenor or benchmark spread. Investors cannot test the pricing claim against the bond’s actual economics.
Ho described refinancing existing project indebtedness as the transaction’s key complexity. It required careful coordination among the outgoing and incoming security agents, their respective lawyers and other parties under a tightly coordinated closing timetable. The transition covered the share charge, accounts charge and vessel mortgage.
The closing sequence included discharging the existing vessel mortgage and registering the new mortgage with the Maritime and Port Authority. The parties coordinated that transfer to preserve a seamless transition between the security packages.
Takeaway: Singapore law supplied the legal architecture for collateral on an Angola-based vessel.
Who advised and arranged the offering?
TSMP served as Singapore counsel to Yinson Azalea Production. Partner June Ho led the team. Associate director Heather Chong and senior associate Markus Low supported her.
Skadden Arps Slate Meagher & Flom advised Yinson Azalea Production on US and English law. PRIME Advogados assisted on Angolan law. Gibson Dunn represented the global coordinators and joint bookrunners.
The joint bookrunners included:
- Citigroup Global Markets Singapore;
- The Hongkong and Shanghai Banking Corporation, Singapore branch;
- JP Morgan Securities Asia; and
- Banco Santander, Singapore branch.
First Abu Dhabi Bank PJSC, MUFG Securities Asia, Singapore Branch, and Samuel A Ramirez & Co acted as co-managers.
Takeaway: The financing combined Singapore, US/English and Angolan counsel with four named joint bookrunners and three co-managers.
What should investors watch next?
The source supports the deal size, collateral structure and use of proceeds. It does not disclose the coupon, yield, tenor, old debt balance, charter revenue or debt-service schedule. Neither the cost of the new capital nor any saving from the refinancing can be calculated from the announcement.
Ho’s assessment of attractive pricing remains adviser commentary rather than a measured result. The 15-year charter provides the operating context, but the announcement provides no figures for testing debt-service capacity against contracted revenue.
Takeaway: Investors know the bond size and collateral, but not the economics of the refinancing.
Watch item: Follow-up disclosure of the coupon, yield, tenor and old debt balance would provide the first usable test of Ho’s market-demand claim.
via Google News: Offshore drilling and FPSOs (Source)
More from Priya Raman
Show full bio
Senior reporter covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
560 articles