Well report No. RR-6078 · T10N · R35W · SEC 22 · filed October 10, 2026
OffshoreWell report
Yinson Production prices USD 1.458B bond to refinance Agogo FPSO
Yinson Production priced a USD 1.458 billion project bond to refinance the Agogo FPSO, the largest single-FPSO project-bond transaction the operator has executed to date.
Field notes
- Yinson Production priced a USD 1.458 billion project bond to refinance the Agogo FPSO.
- The transaction is the largest FPSO project-bond issuance the operator has executed to date.
- Proceeds will replace construction-era financing taken at the Agogo unit's financial close.
- The pricing was disclosed through a corporate announcement carried by EIN News.
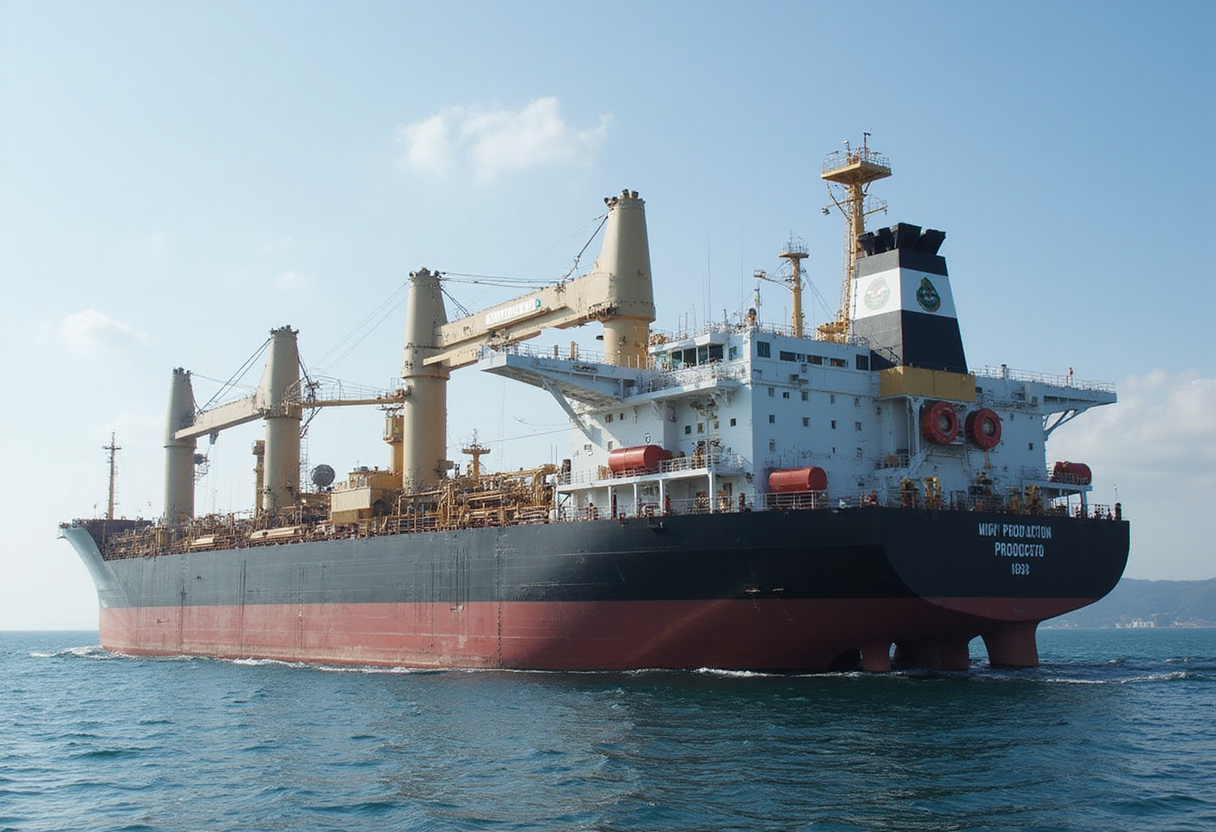
Yinson Production priced a USD 1.458 billion project bond to refinance the Agogo FPSO, marking the largest FPSO project-bond transaction the operator has executed to date, according to a corporate announcement carried by EIN News.
Proceeds will retire the original financing package put in place when the Agogo unit reached financial close, replacing construction-era debt with permanent capital at a longer tenor.
How does the deal size compare with the broader FPSO project-bond universe?
Project bonds tied to a single FPSO remain a niche slice of the offshore energy capital stack. They sit alongside reserve-based lending, mezzanine tranches and sponsor equity, and they allow operators to lock in long-tenor funding against the contracted cash flows of one vessel.
Pricing typically tracks the credit quality of the charter counterparty and the residual value of the hull. At USD 1.458 billion, the Agogo bond ranks among the larger single-vessel deals in the FPSO market.
Most mid-size FPSO refinancings sit well below USD 1 billion. Only the largest newbuilds — vessels heading to Guyana, Suriname or Brazil's pre-salt — routinely push above the USD 1.5 billion mark at issuance.
The Agogo transaction sits at the upper end of the market but below the top-of-cycle Guyana deals, a positioning that should broaden its appeal to institutional investors sizing FPSO exposure. It also extends a multi-year trend of larger single-vessel refinancings as operators consolidate construction and bridge facilities into a single project-bond takeout.
What does the refinancing change operationally?
Operationally, very little. The unit itself continues producing under its existing charter. What changes is the debt line on the project's balance sheet.
Refinancing at this scale typically targets one of three goals: extending tenor to match the remaining field life, replacing construction-stage bridge debt with permanent capital, or capturing a lower coupon if credit conditions have improved since financial close.
A deal this size will reset the comparable market for any follow-on FPSO bond issuance in the next twelve to eighteen months, particularly for operators with similar contract profiles in the same basins.
Lead arrangers typically market these transactions to insurance accounts, infrastructure funds and dedicated energy-credit funds, with allocations weighted toward investors comfortable with long-dated single-asset paper.
What does the Agogo bond signal about FPSO credit?
The deal suggests continued confidence in long-dated FPSO cash flows among institutional investors, despite the cyclical nature of offshore project finance.
The 2014–2017 oil downturn thinned the market for FPSO paper. The recovery since 2022 has brought new entrants and larger transactions. A USD 1.458 billion single-vessel deal is consistent with that recovery.
Pricing also signals that charter counterparty quality remains a differentiator. Investors size FPSO paper against field-life duration, oil offtake terms and the credit quality of the operating counterparty.
The pricing of the Agogo bond, when disclosed in the offering memorandum, will give the market a fresh read on where institutional investors are clearing for top-quality long-tenor paper through the 2025–2026 issuance window.
What is the watch item?
Three dates cluster around the close. First, formal settlement, typically two to three weeks after pricing.
Second, publication of the offering memorandum with the full covenant package, tranche ratings and hedging schedule.
Third, any related hedging transaction on the underlying charter revenue stream, which is often unwound or restructured at refinancing.
The pricing announcement itself is the headline event. The covenant package, tenor and coupon details that follow will determine whether the deal resets the comparable curve for FPSO paper in 2025 and 2026, or whether it stands as a one-off tied to the Agogo unit's specific contract profile.
via Google News: Offshore drilling and FPSOs (Source)
More from Daniel Okafor
Show full bio
Market editor covering consumer brands and retail at Rig & Refinery.
321 articles
Adjoining reports
- Yinson Production Prices $1.458 Billion Bond for Agogo FPSO Refinancing
- Yinson Production prices USD 1.458 billion FPSO bond for Agogo
- Yinson prices US$1.46 billion Agogo FPSO bond package
- Yinson Production Prices Largest FPSO Project Bond to Date
- Yinson Production prices $1.46B in notes to refinance Agogo FPSO