Well report No. RR-2279 · T11N · R31W · SEC 11 · filed November 12, 2026
Upstream Drilling & ProductionWell report
Gerdes Lifts Magnolia Oil & Gas to Buy, $29 Target After Wildfire Close
Gerdes upgraded Magnolia Oil & Gas to Buy with a $29 target after $223.7 million in adjusted free cash flow and leverage below 1x on $1.9 billion net debt.
Field notes
- Gerdes Energy Research upgraded Magnolia (NYSE: MGY) to Buy from Neutral on Tuesday with a $29 price target
- Adjusted free cash flow reached $223.7 million in the first results since the Wildfire acquisition closed
- Net debt of about $1.9 billion put leverage below 1x earnings, ahead of management's original timeline
- Magnolia plans to buy back at least 1% of shares quarterly and has raised its dividend 20% this year
- CEO Christopher Stavros said the stock faces pressure from the Wildfire seller's potential stock sales
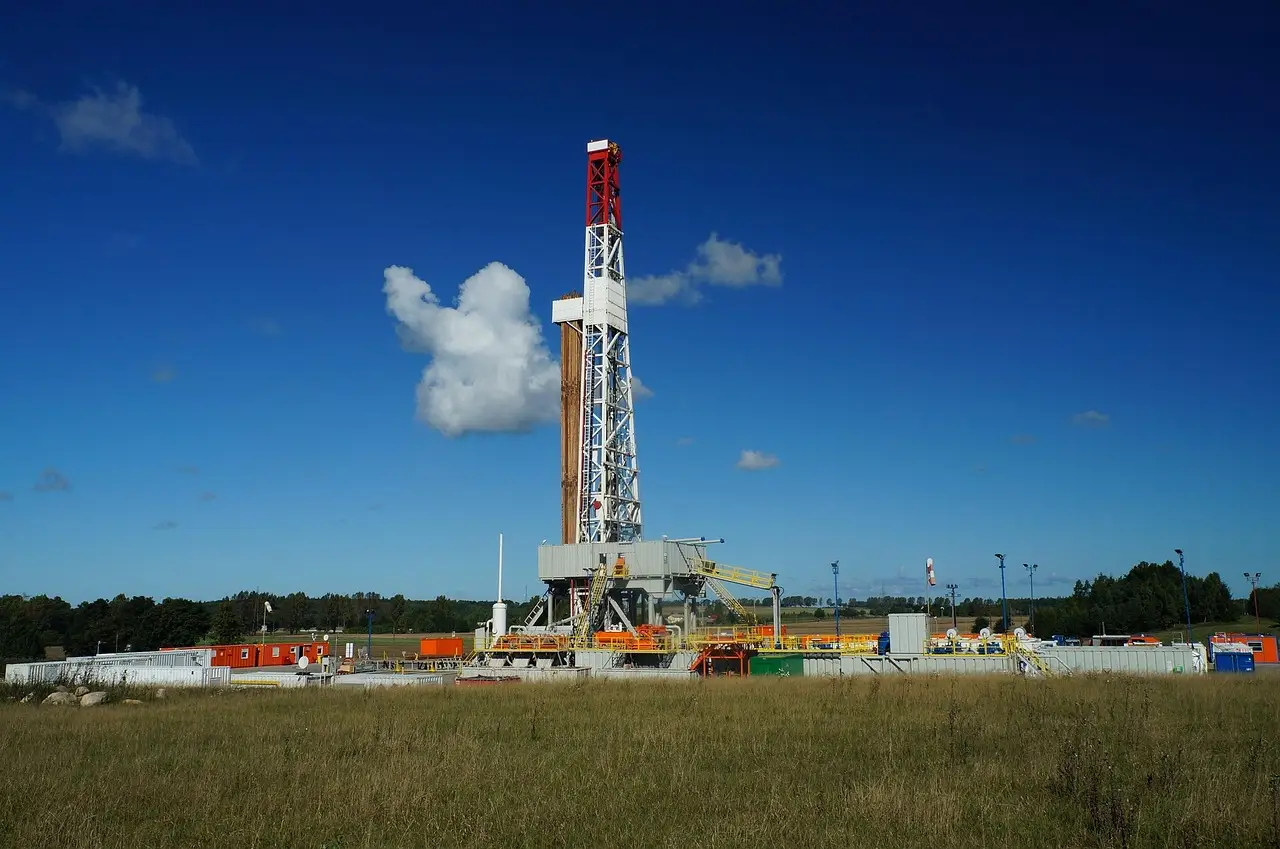
Gerdes Energy Research upgraded Magnolia Oil & Gas (NYSE: MGY) to Buy from Neutral on Tuesday and set a $29 price target. The call follows the company's first results since closing the Wildfire acquisition.
The numbers behind the upgrade are operational. Adjusted free cash flow came in at $223.7 million. Net debt of roughly $1.9 billion put leverage below 1 times earnings, according to the Gerdes note. Management had originally targeted that milestone a year later or more.
Magnolia produces oil and natural gas in Texas. The Wildfire deal added acreage that the company is now integrating with its own rigs and crews.
What drove the faster deleveraging?
Cost savings on the acquired acreage are arriving ahead of plan, the research house noted. Magnolia has already swapped in its own rigs and crews on the Wildfire properties, cutting operating costs faster than the integration schedule anticipated.
That speed shows up in the balance sheet. Leverage below 1x, reached quarters early, gives the company room to press ahead with shareholder returns while it digests the acquisition.
The takeaway: the upgrade rests on delivered numbers, not projections.
How is management answering the share overhang?
Chief Executive Officer Christopher Stavros addressed the stock's recent weakness directly. He said the shares have felt pressure because the seller of Wildfire received stock in the deal and may sell some of it.
Magnolia's response is to keep returning cash to shareholders. The company plans to buy back at least 1% of its shares every quarter. It has also raised its quarterly dividend by a cumulative 20% this year.
These measures are intended to support the stock while the company integrates the acquisition and delivers on its deleveraging and cost-savings goals.
The buyback pace, at minimum 1% per quarter, implies roughly 4% of shares retired annually at the floor.
What is the watch item?
JPMorgan has also wagered that Magnolia can break to new highs, a recap of that position offers detail on how analysts view the stock.
Price commentary here reflects analyst opinion, not settled fact. The $29 target and the bullish positioning stand or fall on continued execution.
Investors should track three markers in coming quarters: sustained free cash flow above $200 million, maintenance of sub-1x leverage, and the pace at which the Wildfire seller reduces its stock position. The quarterly buyback and dividend cadence will show whether management keeps its floor commitments while integration proceeds.
via tradingview.com (Source)
More from Olivia Hart
Show full bio
Correspondent covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
570 articles
Adjoining reports
- Magnolia Exits Dimmit, Zavala Counties for $47.5 Million
- APA lifts 2027 capex to $2.5 billion, half the increase for exploration
- DOE closes first oil production loan: $480m for Arena's Elkhorn
- Patterson-UTI: Higher Prices Won't Spur More US Production
- EOG expands Ohio Utica with 95 wells and an in-basin sand mine