Well report No. RR-7485 · T9N · R33W · SEC 33 · filed November 12, 2026
Well report
SBM Offshore Lifts Full-Year Guidance a Third Time on FPSO Sales
SBM Offshore raised full-year revenue guidance to $7.9 billion on 132% turnkey sales growth, with the FPSO One Guyana sale leading and net debt down 36%.
Field notes
- Full-year directional revenue guidance raised to about $7.9 billion from $7.6 billion — third upgrade this year.
- Turnkey unit sales grew 132% year on year to $4.6 billion, boosted by the February FPSO One Guyana sale.
- Year-to-date directional revenue rose 77% to $6.3 billion; directional net debt fell 36% to $3.6 billion.
- 2026 directional EBITDA now expected to exceed $1.95 billion, up from around $1.9 billion.
- Fleet producing more than 2 million boe/d at roughly 99% uptime; CEO cites 16 FPSO opportunities over three years.
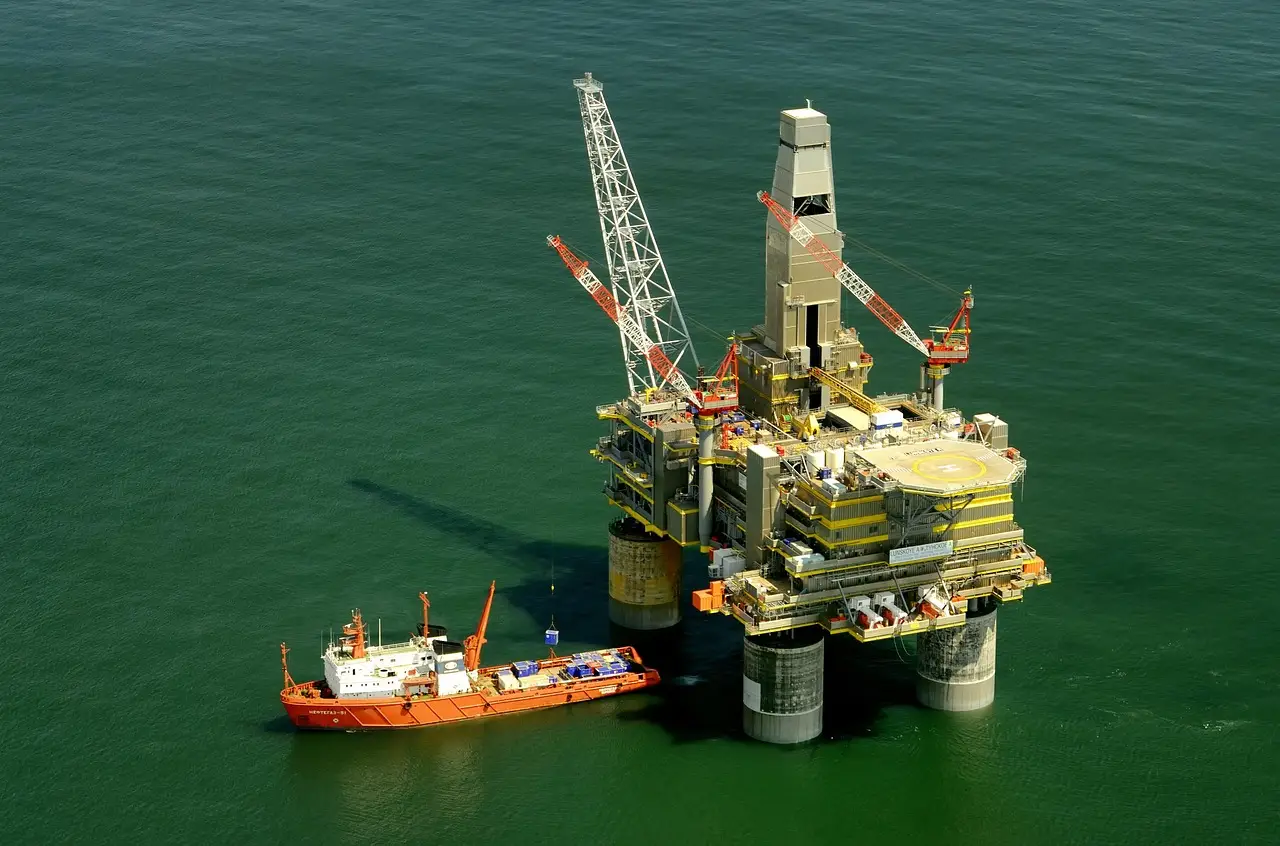
SBM Offshore raised its full-year revenue guidance to about $7.9 billion on Thursday, up from $7.6 billion, in the Dutch floating production specialist's third upgrade this year. The company also lifted its directional EBITDA outlook for 2026 to more than $1.95 billion, against a previous forecast of around $1.9 billion.
The driver is clear enough: the turnkey unit, which builds and sells floating production vessels to oil and gas companies, grew sales 132% year on year to $4.6 billion. The February sale of the FPSO One Guyana, along with other contracts, did most of the heavy lifting.
What did the quarter deliver?
Year-to-date directional revenue climbed 77% to $6.3 billion, the company said in a statement. Directional net debt fell 36% from year-end 2025 to $3.6 billion.
The leased and operated fleet kept pace. SBM Offshore said its vessels are producing more than 2 million barrels of oil equivalent per day, with uptime running at around 99%.
In short, the company is selling more units while running the fleet it still owns at near-full utilization.
How does the FPSO pipeline look?
CEO Oivind Tangen pointed to a backlog of prospects rather than a single project. "The FPSO market outlook remains strong, with 16 opportunities in our sweet spot expected over the next three years," Tangen said in a statement.
Those opportunities represent appraisal-stage pipeline, not sanctioned work — the company has flagged them as targets, and conversion into firm contracts will depend on operator investment decisions. The One Guyana sale, by contrast, is delivered revenue, booked against ExxonMobil's deepwater development offshore Guyana.
The takeaway: SBM Offshore's guidance rests on completed sales, while the growth story ahead depends on how many of those 16 prospects convert.
What's the watch item?
Investors will be watching whether the turnkey order book keeps feeding itself. A third guidance raise in a single year sets a high bar, and the 2026 EBITDA figure above $1.95 billion now frames expectations for the next reporting cycle.
The number to track is conversion — how many of the 16 identified FPSO opportunities land as signed contracts over the coming quarters.
via oedigital.com (Source)
More from Elena Vasquez
Show full bio
News editor covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
578 articles
Adjoining reports
- SBM Offshore, ExxonMobil clear FEED gate on next Guyana FPSO
- ExxonMobil sanctions $12.5B Longtail development offshore Guyana
- SBM Offshore, Petrobras Sign $12-Billion Deal for FPSO Pair
- SBM Offshore FPSO Award Opens FEED Gate on ExxonMobil Guyana Project
- Guyana Crude Exports Near 1 Million BPD Mark for First Time