Well report No. RR-2897 · T11N · R30W · SEC 35 · filed November 6, 2026
Upstream Drilling & ProductionWell report
Devon closes portfolio review with Eagle Ford sale, keeps four basins
Devon Energy ends its strategic review with a $4.2bn Eagle Ford sale to Crescent, keeping 900,000 boe/d of Permian output and planning $5.3bn of 2025 capital.
Field notes
- Devon agreed to sell its Eagle Ford assets to Crescent Energy for $4.2 billion.
- Post-sale, Devon will hold ~750,000 net Permian acres producing ~900,000 boe/d.
- 2026 capital plan: $5.3 billion, three-quarters allocated to the Permian.
- Early 2027 forecast: total production up 2.6% to 1.6 million boe/d.
- DVN shares fell 1.4% to $42.26 on Nov. 6; market value stands at $46.5 billion.
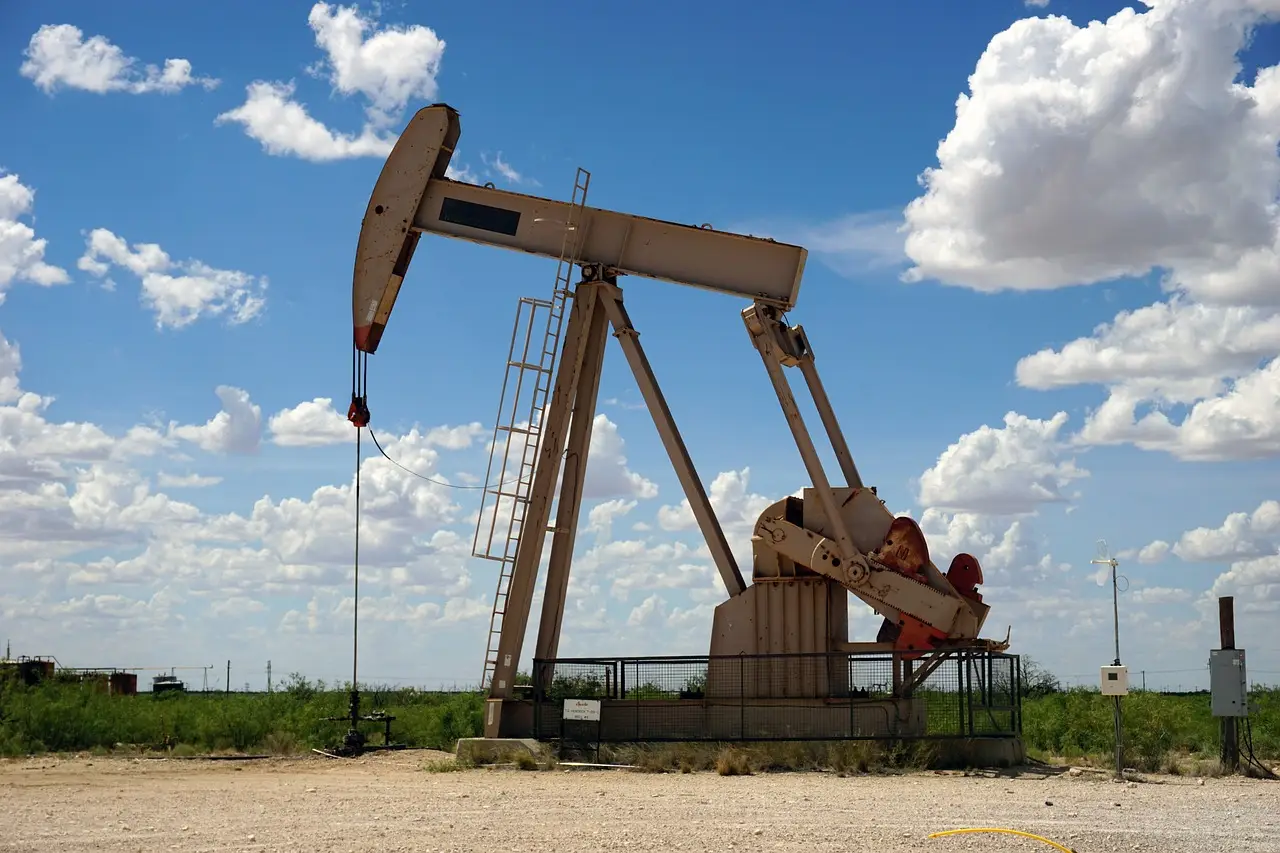
Devon Energy Corp. has capped its portfolio review with a $4.2 billion Eagle Ford divestiture and a plan to hold roughly 900,000 boe/d of Permian production plus three other producing regions — a stance that drew immediate pushback from activist investors and a 1.4% share decline on Nov. 6.
President and CEO Clay Gaspar told analysts on Devon's third-quarter call that the company's board "will not hesitate" to strike further deals if they serve shareholders, but that the strategic-review chapter in which "everything's on the table" is now closed.
What did the review produce?
The review followed Devon's acquisition of Coterra Energy and the agreement to sell its Eagle Ford operations to Crescent Energy Co. for $4.2 billion. Assuming that sale closes, Devon will control:
- About 750,000 net acres in the Permian basin, producing roughly 900,000 boe/d
- The Anadarko basin, at 177,000 boe/d
- The Williston and Powder River basins, at a combined 187,000 boe/d
- Marcellus shale gas assets, at about 2 bcfd
Gaspar described the non-Permian holdings as "complementary assets" rather than candidates for sale.
The months of review were, in his words, "taxing" for employees and investors alike, given persistent uncertainty over strategy. Some shareholders had pressed Devon to sell the non-Permian assets outright and concentrate on the Delaware and Midland, or to put the entire company up for sale. Neither is happening in the near term, though Gaspar said his team remains open to conversations with bidders.
"We owe it to our investors to […] be thorough, very transparent and very open, but we also found it very important that we drew a line and said, 'This is the close of this period, this chapter,'" Gaspar said.
What does the capital plan look like?
Devon has penciled in $5.3 billion of capital spending for next year, with three-quarters of that directed at the Permian. The retained assets are slated to grow production 1-3% annually in coming years.
Early forecasts for 2027 call for Devon, excluding the Eagle Ford, to lift total output 2.6% to 1.6 million boe/d.
Asked about Devon shares trading at a discount to peers, Gaspar framed the review's conclusion as the remedy.
"We're going to work on getting better every single day for the best interest of the shareholders," he said. "I think that clears the path to close this valuation gap and we look forward to being on the road as soon as Monday to meet with more investors."
How did investors respond?
Not well. TOMS Capital Investment Management, which alongside Kimmeridge had pushed for more drastic action, said in a Nov. 6 statement it is "profoundly disappointed" that Devon is holding station — while acknowledging management's commitment to engage with potential buyers.
The market's verdict was similarly cool. Devon shares (DVN) fell 1.4% to $42.26 in afternoon trading while many U.S. peers gained. Over the past six months the stock has shed nearly 10% of its value, cutting Devon's market capitalization to $46.5 billion.
The watch item: whether the Eagle Ford sale to Crescent closes on schedule — and whether Gaspar's investor roadshow, starting the week of Nov. 10, narrows that valuation gap before activists escalate.
via s2.q4cdn.com (Original)
More from James Calloway
Show full bio
Staff writer covering people, launches and day-to-day practice in Oil and gas industry operations and markets at Rig & Refinery.
564 articles
Adjoining reports
- Devon to divest Eagle Ford package to Crescent Energy for $4.2bn
- Crescent to Buy Devon's Eagle Ford Assets for $4.2 Billion
- Ovintiv to Pay $890m for Logan Energy, Adding 266,000 Montney Acres
- Chevron to divest Hess Midstream stake and DJ Basin assets
- ONEOK closes $4.43bn Brazos Midstream deal, doubles Midland capacity