Well report No. RR-1288 · T12N · R49W · SEC 36 · filed November 10, 2026
Upstream Drilling & ProductionWell report
Marcellus/Utica holds at 33 rigs as U.S. count hits 604
Marcellus/Utica rigs held at 33 for a 10th week, while the U.S. count reached 604. Devon left Enverus's permit list as EQT and EOG tied for the top rig position.
Field notes
- The Marcellus/Utica held at 33 rigs for the week ended Nov. 6, a 10-week stretch.
- The U.S. rig count rose one to 604, a 52-week high.
- Oil and gas rigs each increased by one, while frac spreads rose four.
- WTI fell 12.76% to $90.83; December natural gas rose $0.10 to $2.998/MMBtu.
- Devon left Enverus's permit list after four weeks at nine permits.
What changed in the rig count?
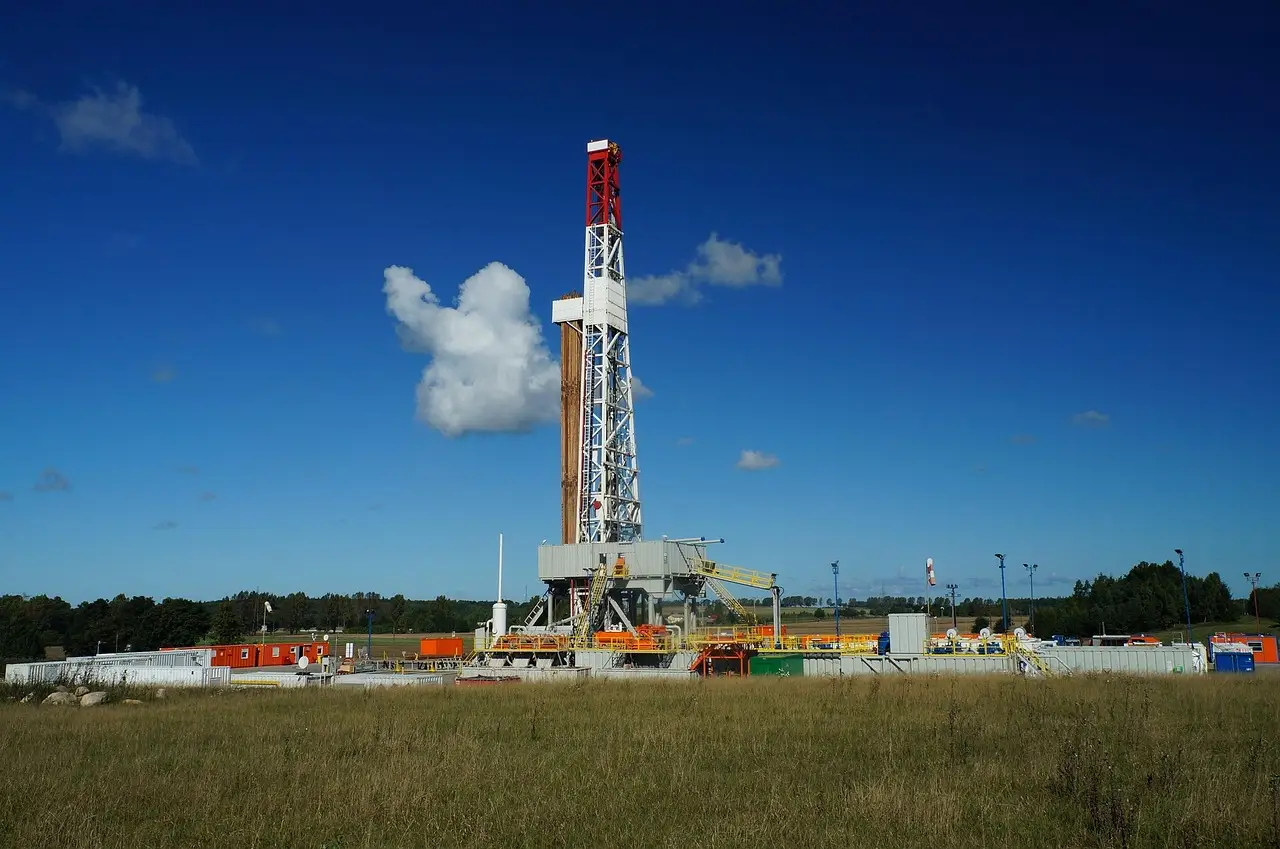
The Marcellus/Utica held at 33 rigs for the week ended Nov. 6, extending the area's tally to 10 weeks without a change. The weekly rig-count summary framed it plainly: “Ten weeks. Still 33.”
That stability contrasts with the national increase, although the report does not identify which operators or drilling types account for the unchanged Marcellus/Utica tally.
Across the U.S., the count moved from 603 to 604, ending a four-week hold and setting a 52-week high. The gain was small, but it covered both drilling types. Oil rigs rose by one. Gas rigs rose by one.
Frac spreads (active hydraulic-fracturing crews) climbed by four, ending a three-week slide. The report gives no basin breakdown for that increase. It therefore cannot be assigned confidently to the Marcellus or Utica from these figures.
WTI (West Texas Intermediate) fell 12.76% for the week to $90.83 a barrel. December natural gas rose 10 cents to $2.998 per MMBtu (million British thermal units), leaving the contract just below $3. The report gives the price moves as market context. It does not connect either series to rig decisions, producer margins or service activity.
In plain terms: the national rig count reached a yearly high, while the Marcellus/Utica stayed flat.
What do the permit changes show?
The rig count and the permit list answer different questions. A rig count measures active drilling. A permit list records locations cleared for drilling, not work already underway.
The source does not say that a listed permit becomes a rig on a fixed schedule. The permit changes should not be treated as confirmed drilling or production.
Devon dropped off Enverus's permit list after spending four weeks at nine permits. The report does not state the cause, the locations affected, or whether any rig count followed the removal, so the commercial significance remains unclear. It should therefore be read as a permit-list change, not evidence of an immediate production increase or decrease.
Range Resources' permits also fell “back to earth,” according to the report, but the available figures provide no revised total. No new basin allocation or operator detail accompanies the change. That limits any conclusion about whether Range's decline offsets Devon on the permit list or alters drilling activity in the Marcellus/Utica from these figures.
EQT and EOG now share first place on the rig list. The report gives no absolute count for either company, so the tie establishes rank, not scale. It does not link that ranking to Devon's permit-list exit.
In plain terms: Devon left the permit list, Range lost permits, and two operators share first place, but the figures do not connect those developments to a basin-level rig move.
What should readers watch next?
The next Marcellus/Utica reading will show whether 33 becomes an 11-week plateau or gives way to a deployment. The national comparison is 604, a 52-week high. Another weekly increase would extend that record.
For permit tracking, watch whether Devon reappears, Range's total becomes available and EQT and EOG's shared rank separates.
Price direction adds context, not a stand-alone forecast. WTI at $90.83 after a 12.76% weekly fall and December gas at $2.998 after a 10-cent rise were sharply different weekly moves. Neither move proves that drilling economics, service demand or company budgets changed in the same way. Without well costs, service costs and company budgets, the price data cannot establish a margin outcome.
That leaves the practical watch list narrow: permit-list changes, the next basin rig count and evidence tying prices to producer margins. The margin remains the key unresolved variable because the report provides prices but no cost data.
via marcellusdrilling.com (Source)
More from Priya Raman
Show full bio
Senior reporter covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
594 articles