Well report No. RR-9382 · T12N · R40W · SEC 24 · filed November 14, 2026
Petroleum MarketsWell report
Okeanis Downgraded to Buy as VLCC Charters Cap Q4 2026 Upside
Okeanis Eco Tankers beat Q3 with $7.67 EPS and a $7 dividend, but chartering out most VLCCs caps Q4 upside and triggered a downgrade to buy.
Field notes
- Okeanis Eco Tankers posted Q3 EPS of $7.67, beating estimates, with a $7 dividend
- Analyst downgraded ECO to buy after the company chartered out most of its VLCCs, limiting Q4 2026 upside
- Chartering improves 2027 visibility, with projected $22.5 EPS and $20 dividend at a $100 fair value
- Key risks cited: vessel attacks and tanker rate normalization
- Analyst discloses a beneficial long position in ECO shares
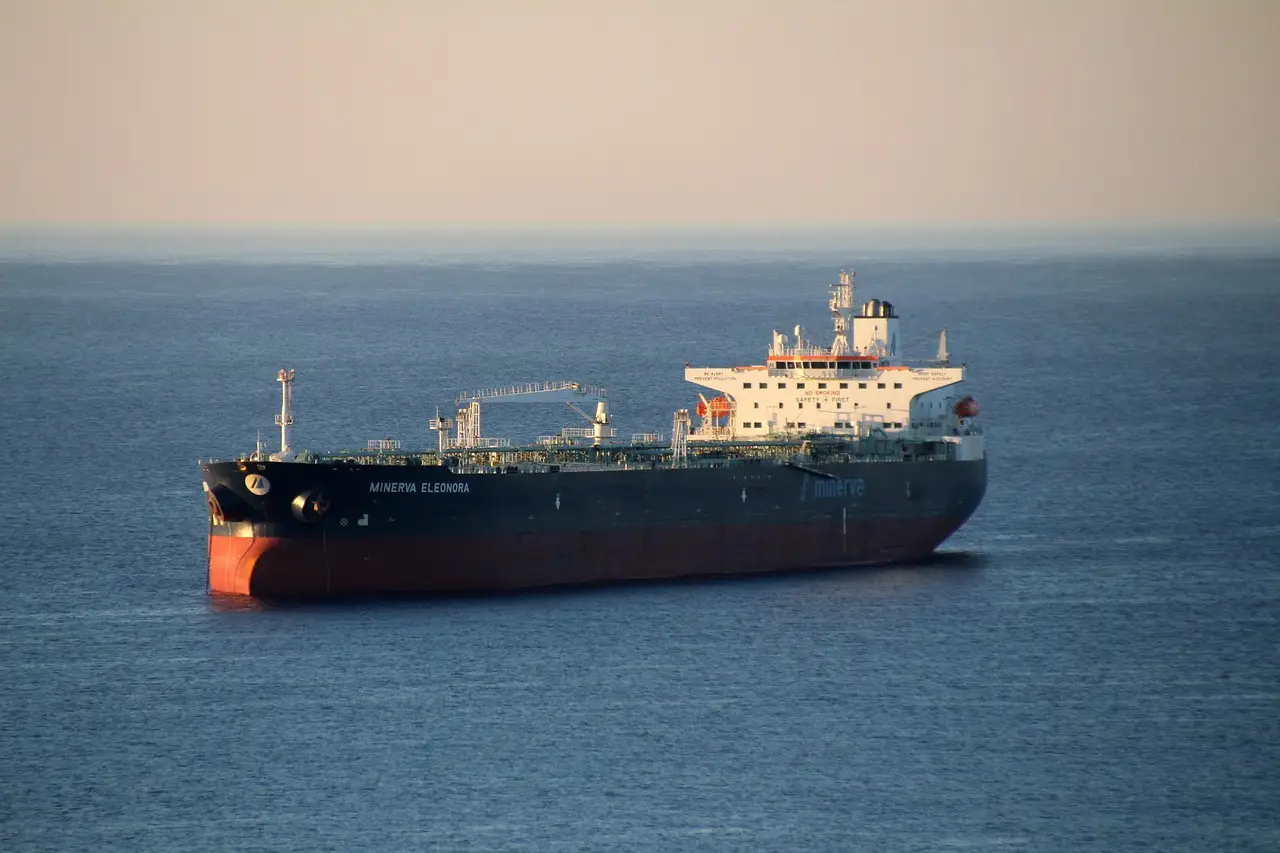
Okeanis Eco Tankers Corp. (ECO) drew a downgrade from buy to a lower conviction rating after chartering out most of its very large crude carriers — a move that locks in revenue but trims fourth-quarter 2026 upside, according to a Seeking Alpha analyst who has covered the company across multiple articles and holds a long position in the shares.
The downgrade is a valuation call, not a distress signal. The analyst previously upgraded the stock and now sees the derisking charters as the reason to step back from the higher rating.
What did Q3 deliver?
The numbers came in strong. Okeanis posted third-quarter earnings per share of $7.67, beating the analyst's estimates, and paid a $7 dividend for the quarter.
That beat, though, runs straight into softer guidance. Management's fourth-quarter outlook is lower than the prior quarter's run-rate, and the reason is structural: most of the VLCC fleet is now fixed on charters rather than exposed to spot tanker rates.
The takeaway: Q3 was the earnings peak for this cycle of the story, and Q4 will look smaller by design.
Why would chartering out the fleet trigger a downgrade?
It sounds counterintuitive — locking in revenue usually reads as good news — but the mechanics cut both ways for an equity story built on rate leverage.
The analyst lays out the trade-off plainly:
- Chartering out most of the VLCCs caps the upside if spot tanker rates keep climbing through Q4 2026.
- In exchange, the fixed employment dramatically improves earnings visibility into 2027.
- That visibility supports a projected EPS of $22.5 for 2027 and a projected $20 per-share dividend at the analyst's $100 fair value for the stock.
So the downgrade reflects a narrower gap between the derisked earnings stream and the market price, not a deterioration in the business. The analyst frames the chartering program as improving 2027 earnings visibility — a phrase that sits at the center of the whole call.
The takeaway: the fleet traded spot-market torque for contracted cash flow, and the stock's reward profile changed with it.
What are the risks?
Two hazards sit at the top of the analyst's list, and both could move the valuation materially.
The first is vessel attacks. Escalation in shipping lanes — the kind that has roiled tanker markets before — remains an open variable for any owner trading Middle East and adjacent crude routes.
The second is tanker rate normalization. The bullish case leans on elevated freight rates holding up; if rates settle back toward historical norms, the earnings stream and the $100 fair value would both come under pressure, charter coverage notwithstanding.
The analyst's disclosure notes a beneficial long position in ECO shares through stock ownership, options, or other derivatives — so the downgrade comes from inside a holder, not a skeptic on the sidelines. The article was self-authored, expresses the analyst's own opinions, and no compensation was received beyond the platform's payment.
The takeaway: an owner-analyst with skin in the game still sees the risk set as real enough to cut the rating.
What's the watch item from here?
The number to track is the 2027 trajectory: whether the projected $22.5 EPS and $20 dividend hold as the chartered VLCCs earn out, and whether spot rates normalize or stay elevated enough to make the derisking look conservative in hindsight.
Until then, the downgrade stands as a measured verdict: the charters bought visibility and sold upside, and at current levels the analyst wants less of the trade.
via seekingalpha.com (Source)
More from Elena Vasquez
Show full bio
News editor covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
578 articles
Adjoining reports
- International Seaways Books 53% of Q4 as Q3 Beats by 16.7%
- Occidental flags Q3 2026 hit from Gulf of Mexico downtime
- BP's Q3 Numbers: An 11% Debt Cut and a Skeptic's Checklist
- WTI Traders Target $88.20 Before a Test of the $83.88 Floor
- WTI tops $105 as Saudi Arabia cancels crude cargoes after pipeline shutdown