Well report No. RR-4683 · T19N · R46W · SEC 7 · filed October 10, 2026
OffshoreWell report
Rockhopper to acquire 35% OSX-1 FPSO stake for $44m
Rockhopper has agreed to pay $44m for a 35% interest in the OSX-1 FPSO vessel, per Investing.com Canada. The deal implies a gross asset value near $126m; field deployment and counterparty remain undisclosed.
Field notes
- Rockhopper to pay $44m for a 35% interest in the OSX-1 FPSO vessel
- Headline implies a gross asset value of approximately $126m for the unit
- The OSX-1 is a floating production, storage and offloading (FPSO) vessel
- Field deployment, throughput capacity, water depth and counterparty not disclosed in the source brief
- Reported by Investing.com Canada; transaction terms await confirmation by regulatory filing
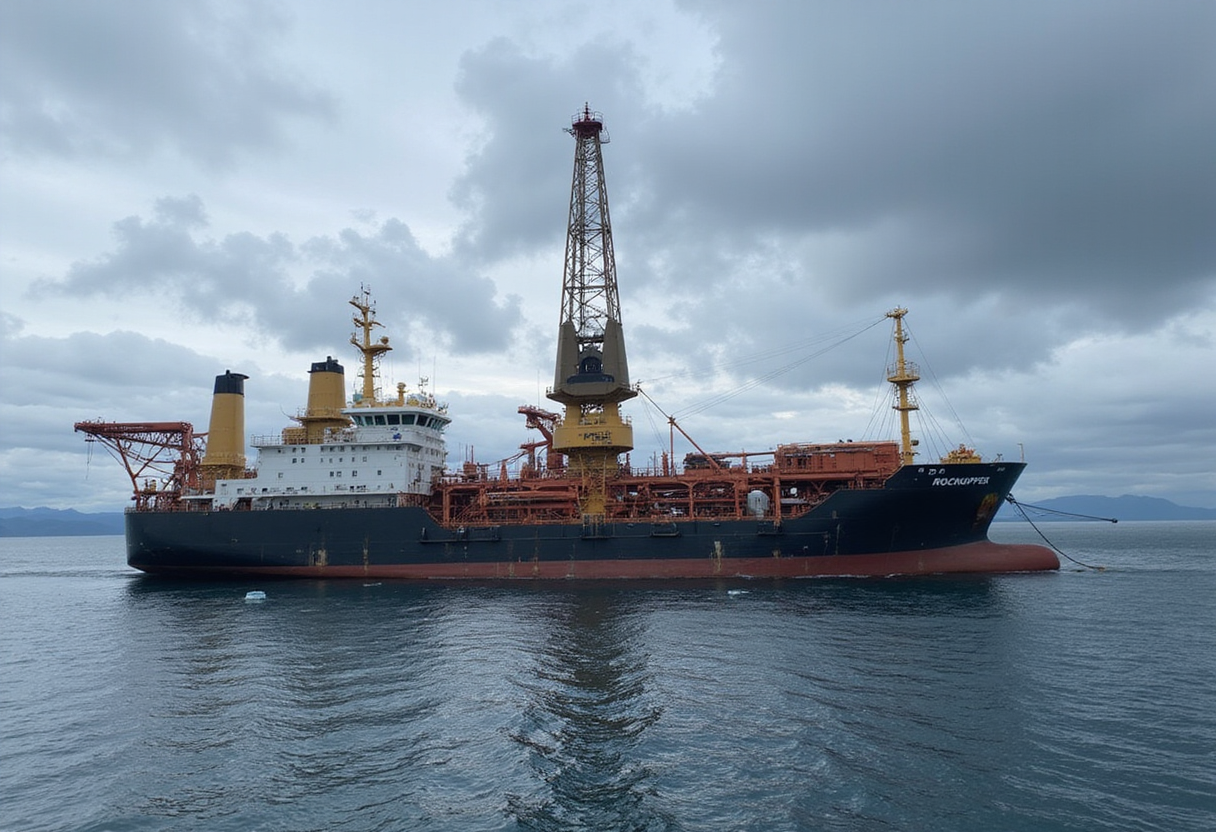
Rockhopper has agreed to pay $44 million for a 35% interest in the OSX-1 floating production, storage and offloading (FPSO) vessel, according to an Investing.com Canada report.
The headline figure implies a gross asset value of approximately $126 million for the unit, based purely on the disclosed consideration. FPSO transactions are typically benchmarked against daily charter rates, throughput capacity, and remaining field life, and the implied valuation here is consistent with a deal struck on an operating-lease or co-ownership basis rather than at the higher multiples attached to producing acreage.
What does the deal change for the acquirer?
The buyer, named in the report as Rockhopper, is taking a minority position in the OSX-1. Minority stakes of this kind generally serve one of three purposes for an upstream junior:
- securing processing capacity for a tied-back development
- gaining exposure to day-rate economics as a non-operating co-owner
- positioning the holder for a possible future operatorship of the host field
Without a counterparty disclosure, the strategic rationale cannot be pinned down from the public record.
The OSX-1 is a redeployable hull whose prior deployments, throughput capacity, and current water depth are not detailed in the Investing.com Canada brief. Independent confirmation from the operator or from a regulatory filing will be required to clarify the field where the unit is currently operating, the contract structure with the host licence group, and the remaining economic life of the assignment.
How is the 35% stake structured?
FPSO ownership at the 35% level most often aligns with a corresponding 35% working interest in the host field's production licence, distributing opex and capex obligations in proportion to entitlement. Where the FPSO stake sits separately from the licence, the holder takes economic exposure to vessel uptime, throughput, and tariff structures without direct production entitlement. The brief does not distinguish between these two structures, leaving the entitlement basis of the Rockhopper interest an open question.
What does the $44m price tell the market?
At $44 million, the deployment is modest in absolute terms but represents a discrete infrastructure allocation for an upstream junior. The implied $126m headline valuation places the per-cubic-metre-of-throughput and per-barrel-of-storage metrics within the range observed for mid-size FPSOs trading in the secondary market in recent quarters. If the unit is on a long-term contract, the trajectory of day-rate exposure over the contract tail will determine whether the 35% interest accretes value above the $44m entry price.
The deal also raises questions about the acquirer's broader portfolio direction. A $44m deployment into a vessel stake can sit alongside continued investment in appraisal and development assets, or it can signal a strategic pivot toward infrastructure-led cash flow. The next regulatory disclosure will determine which interpretation the market settles on, and whether the OSX-1 acquisition opens a path to additional vessel or terminal deals.
For competitors watching the trade, the OSX-1 sale is one of a small number of minority FPSO stakes to clear the market in recent quarters. Secondary-market FPSO transactions tend to cluster around:
- corporate restructuring events
- asset divestments by larger operators
- redeployment of older hulls into new fields
Each of those drivers remains live in the current offshore market, suggesting that further 20–40% stake sales may follow if counterparties seek to monetise non-core infrastructure.
Watch item: the acquirer's next stock-exchange filing confirming the OSX-1 transaction terms, identifying the seller and any remaining co-owners, and disclosing the field where the FPSO is currently deployed and the contract structure attached to the 35% interest.
via Google News: Offshore drilling and FPSOs (Source)
More from Priya Raman
Show full bio
Senior reporter covering media and advertising at Rig & Refinery.
381 articles