Well report No. RR-7003 · T1N · R38W · SEC 25 · filed November 14, 2026
Gas & LNGWell report
FLEX LNG Posts Record Q3 Revenue of $97.4M, Dividend Coverage Gap Widens
FLEX LNG booked record Q3 revenue of $97.4M, up 14% YoY, but LTM adjusted EPS of $2.18 falls short of its $3.00 dividend as cash slid to $370.8M ahead of a tough 2027.
Field notes
- Record Q3 revenue of $97.4 million, up 14% year on year, with adjusted EPS of $0.65 above estimates.
- LTM adjusted EPS of $2.18 covers only about 73% of the $3.00 annual dividend.
- Cash fell from $447.6 million to $370.8 million during 2026.
- 93 newbuild LNG carrier deliveries expected, pressuring rates into 2027 as one-year rates fall and ships come off contract.
- Stock near its 52-week low yields almost 12%; analyst Hold rating with fair value of $24.00-$26.70.
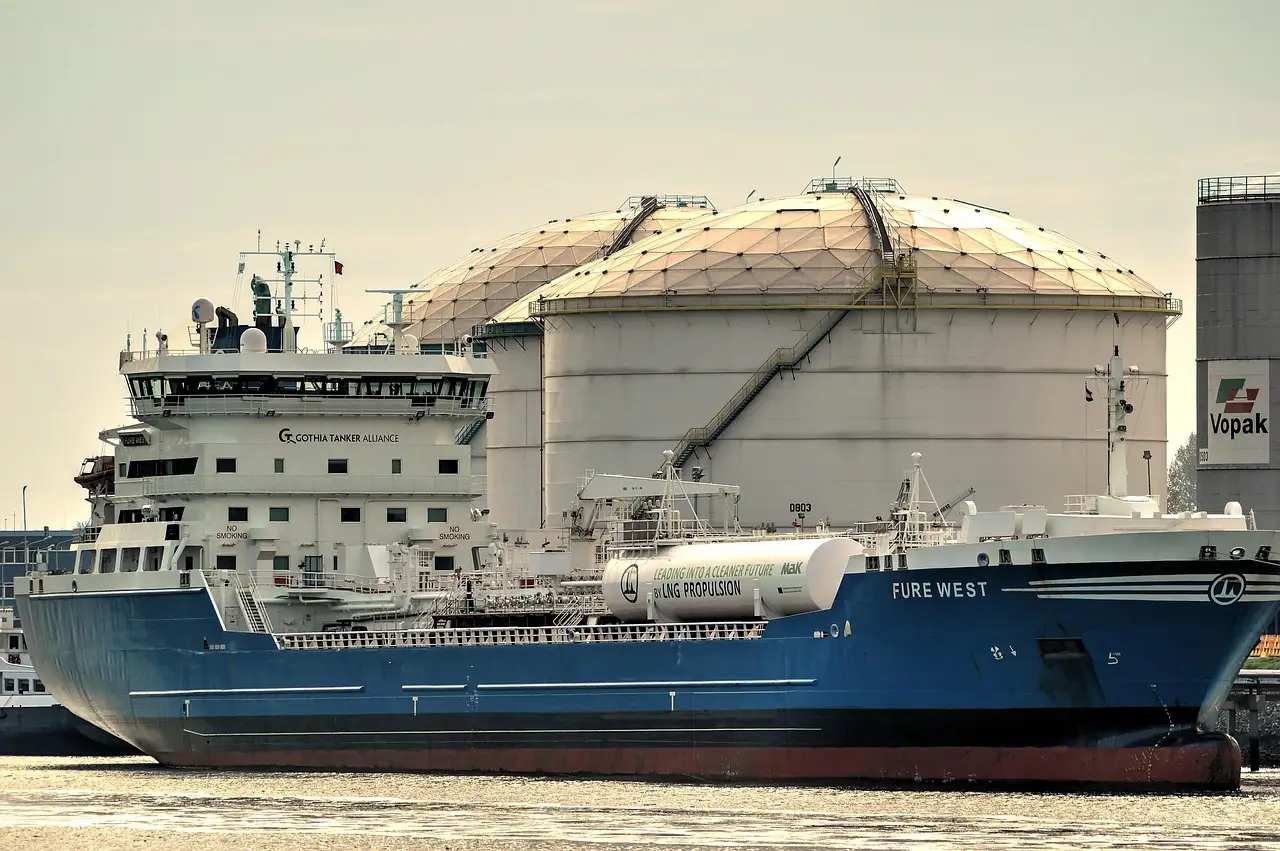
FLEX LNG reported record third-quarter revenue of $97.4 million, up 14% year on year, yet the number that matters most to the market sits below it: adjusted earnings of $2.18 per share over the last twelve months against a $3.00 annual dividend. The Bermuda-based operator of liquefied natural gas carriers (vessels that transport LNG at minus 162 degrees Celsius) is paying out more than it earns, and its cash balance shows it.
What did the quarter deliver?
The topline was the strongest third quarter in the company's history. Revenue reached $97.4 million, a 14% increase from the same period a year earlier. Adjusted earnings per share came in at $0.65, above analyst estimates. On the surface, the quarter reads as operational strength across the fleet.
The picture beneath the headline is less favorable. Last-twelve-month adjusted EPS of $2.18 covers only about 73% of the $3.00 dividend, implying a shortfall of roughly $0.82 per share over that window. Cash on the balance sheet fell from $447.6 million to $370.8 million so far in 2026, a decline of $76.8 million. The company is funding the difference from reserves.
The takeaway: record revenue and estimate-beating EPS still leave the payout uncovered.
Why does 2027 look difficult?
Three pressures converge on the company's next full fiscal year. First, one-year charter rates in the LNG shipping market are falling, and those rates set the repricing terms for vessels returning to the spot market. Second, a portion of the FLEX LNG fleet comes off contract, exposing those ships to weaker prevailing terms. Third, the orderbook delivers 93 newbuild LNG carriers to the global fleet, adding supply capacity that pressures utilisation and day rates across the sector.
The arithmetic is straightforward. More vessels chasing cargoes in a softening one-year rate environment compresses the revenue available per ship, and FLEX LNG's contract expiries land squarely in that window.
The takeaway: fleet growth and rolling contract exposure both point to lower average earnings in 2027 than in 2025.
What does the market already price?
The stock trades near its 52-week low. At that level, the shares yield almost 12% on the current $3.00 dividend — a figure the market typically reads as skepticism that the payout survives intact. A yield of that magnitude, against demonstrated coverage below 100%, signals that investors expect a dividend cut rather than treating the payout as secure income.
The analyst assessment behind these figures rates the shares a Hold, with a fair value range of $24.00 to $26.70. That range frames the equity as roughly fairly valued at present levels: cheap enough to reflect the coverage gap, but not cheap enough to compensate for the 2027 rate and supply risks without a reset to the dividend.
The takeaway: the near-12% yield is the market's verdict, not a free lunch.
What is the watch item?
The dividend decision is the catalyst. A cut would align the payout with the $2.18 earnings run-rate and likely remove the overhang that has pushed the stock toward its 52-week low. Holding the $3.00 dividend would continue drawing down cash at a pace the 2026 balance sheet can no longer comfortably absorb — $370.8 million and falling — particularly with weaker one-year rates and 93 newbuild deliveries approaching in 2027.
Investors should track three markers in coming quarters: the pace of cash decline from the current $370.8 million, the level at which expiring contracts reprice, and any board statement on the distribution. Each figure will signal whether the market's implied expectation of a cut becomes company policy.
The takeaway: watch the cash line and the contract repricing dates — they will decide the dividend before the board says a word.
via seekingalpha.com (Source)
More from Olivia Hart
Show full bio
Correspondent covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
588 articles
Adjoining reports
- Flex LNG Q3 revenue reaches $97 million as fleet TCE nears $79,000
- TotalEnergies Q3 profit doubles as refining margin averages $33.2/bbl
- Enbridge Q3 profit nearly doubles on gas infrastructure gains
- Big Oil Banks Billions but Refuses to Splash the Cash
- Chevron Books $9.9bn Q3 Net Income as Downstream Earnings Nearly Quintuple