Well report No. RR-6097 · T15N · R49W · SEC 3 · filed October 30, 2026
Upstream Drilling & ProductionWell report
Brent Slips to $115/bbl on Iran Diplomacy; TTF Hits 22-Month High
Brent eased 1.6% to about $115/bbl on Oct. 26 on Iran diplomacy hopes, while Dutch TTF gas touched €97.50/MWh, its highest since December 2022, as EU storage sat at 74.6%.
Field notes
- Brent traded near $115/bbl on Oct. 26, down about 1.6%; WTI fell about 2% to $101/bbl.
- Saudi, Pakistani, and Turkish officials were expected to hold security talks with Iranian leaders in Tehran on Oct. 26.
- EU gas storage stood at 74.6% of capacity as of Oct. 25, below late-October historical averages.
- Front-month Dutch TTF futures touched €97.50/MWh on Oct. 26, the highest since December 2022.
- LNG shipment disruptions from Qatar and the UAE constrained European inventory replenishment.
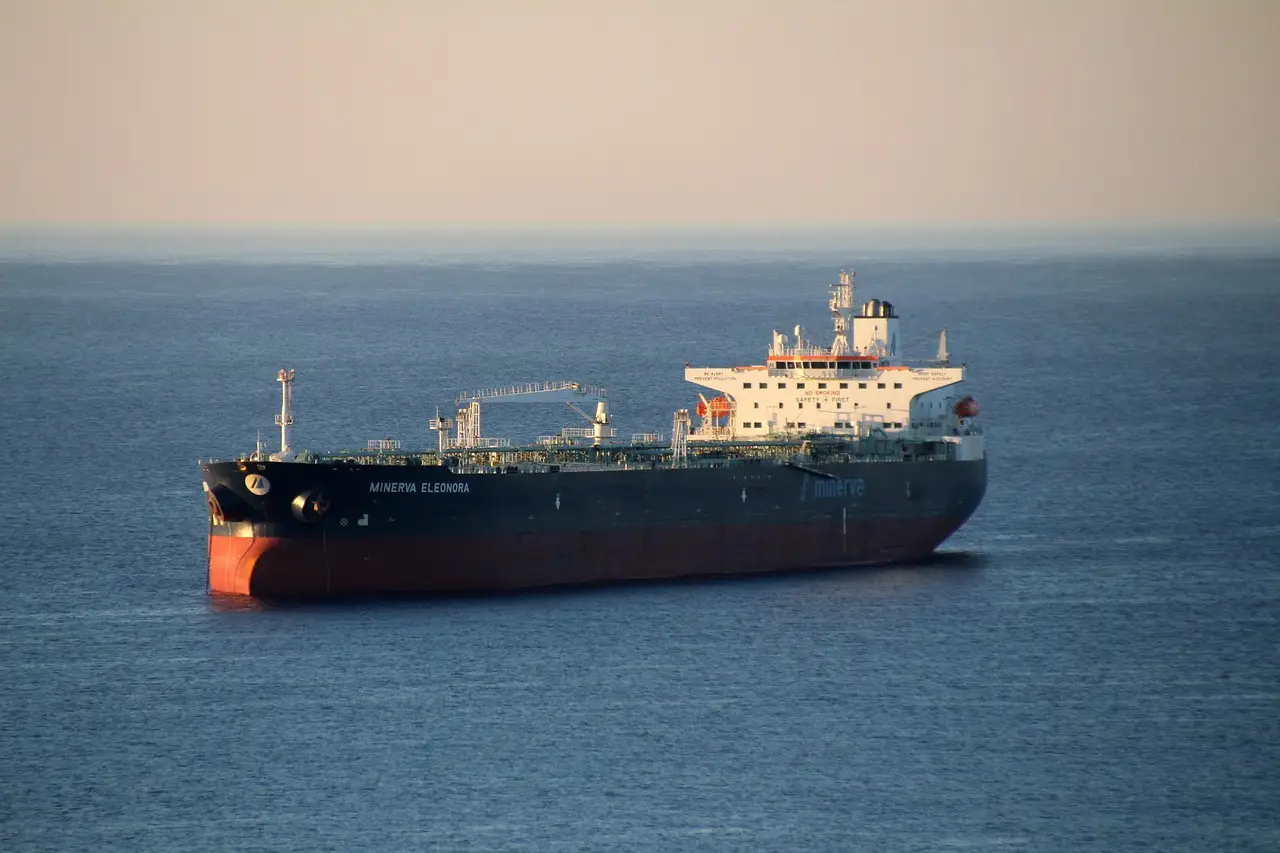
Brent crude traded near $115/bbl on Oct. 26, down roughly 1.6%, as renewed diplomacy between Iran and regional powers tempered the risk premium that had driven both benchmarks to six-month highs. US West Texas Intermediate fell about 2% to $101/bbl in early trading. Both grades remained close to levels set in the prior week's rally.
The pullback is modest. Prices are easing, not collapsing, and the supply-side threats that built the premium remain unresolved.
What drove the dip in oil prices?
Senior officials from Saudi Arabia, Pakistan, and Turkey were expected in Tehran on Oct. 26 for security talks with Iranian leaders. The meeting followed concern that the US and Israel might launch fresh strikes against Iran. Attacks by the Houthi movement against Saudi targets continue to escalate.
Iranian officials said the talks would cover regional conflicts, including the situation in Lebanon, and efforts to establish a security framework led by Middle Eastern nations. Traders read the diplomacy as a marginal de-escalation signal and trimmed long positions accordingly.
The geopolitical floor under prices, however, stays firm. Houthi attacks on Saudi targets persist, and Iranian actions against oil tankers in the Strait of Hormuz continue to fuel deep concerns over the security of oil infrastructure and maritime shipping. The corridor handles a large share of seaborne crude, so any interference there feeds directly into freight and insurance costs, which in turn supports physical differentials.
The takeaway: oil eased on talk, not on any restoration of supply.
Why is European gas moving the other way?
European natural gas moved in the opposite direction. Colder weather and disrupted LNG supplies heightened concerns ahead of the winter heating season.
EU gas storage stood at 74.6% of capacity as of Oct. 25. That figure sits well below historical averages for late October, leaving the continent with less buffer than usual heading into peak demand. Disruptions to LNG shipments from Qatar and the UAE constrained the cargoes available to rebuild inventories.
Competition with Asian buyers for available LNG cargoes added to the pressure on European purchasers. Front-month Dutch TTF futures (the continent's benchmark gas price contract) touched €97.50/MWh on Oct. 26. That is the highest level since December 2022.
The takeaway: Europe is entering winter short on storage and short on cargoes at the same time.
What should the market watch next?
Three variables will set direction from here.
- The Tehran security talks: any concrete framework agreed by Saudi, Pakistani, Turkish, and Iranian officials could accelerate the oil risk premium's decay; a breakdown would restore it quickly.
- Strait of Hormuz and Houthi activity: continued tanker interdictions or strikes on Saudi infrastructure would offset diplomatic progress on the oil side.
- Winter weather and Qatari and Emirati LNG flows: TTF's path above €97.50/MWh depends on whether cargo disruptions ease before storage draws begin in earnest, and on how hard Asia bids against Europe for spare volumes.
Price commentary in this report reflects market analysis as of the Oct. 26 session and should be treated as attributed observation, not settled fact.
The watch items: the outcome of the Tehran talks, the next Houthi or Hormuz incident, and the EU storage fill rate as November begins.
via Oil & Gas Journal (Source)
More from Olivia Hart
Show full bio
Correspondent covering technology and product news in Oil and gas industry operations and markets at Rig & Refinery.
556 articles
Adjoining reports
- WTI Jumps 2.1% to $93.78 on Saudi Attacks Near Hormuz
- Brent Holds Above $100 as Hormuz Tanker Traffic Sinks to Two-Month Low
- Brent climbs 2.25% to $105.40 on stalled US-Iran diplomacy
- WTI swings $12/bbl as Yanbu exports ease to 5.5 million b/d
- Brent and WTI Jump as Houthi Attacks Fuel US-Iran Escalation Fears